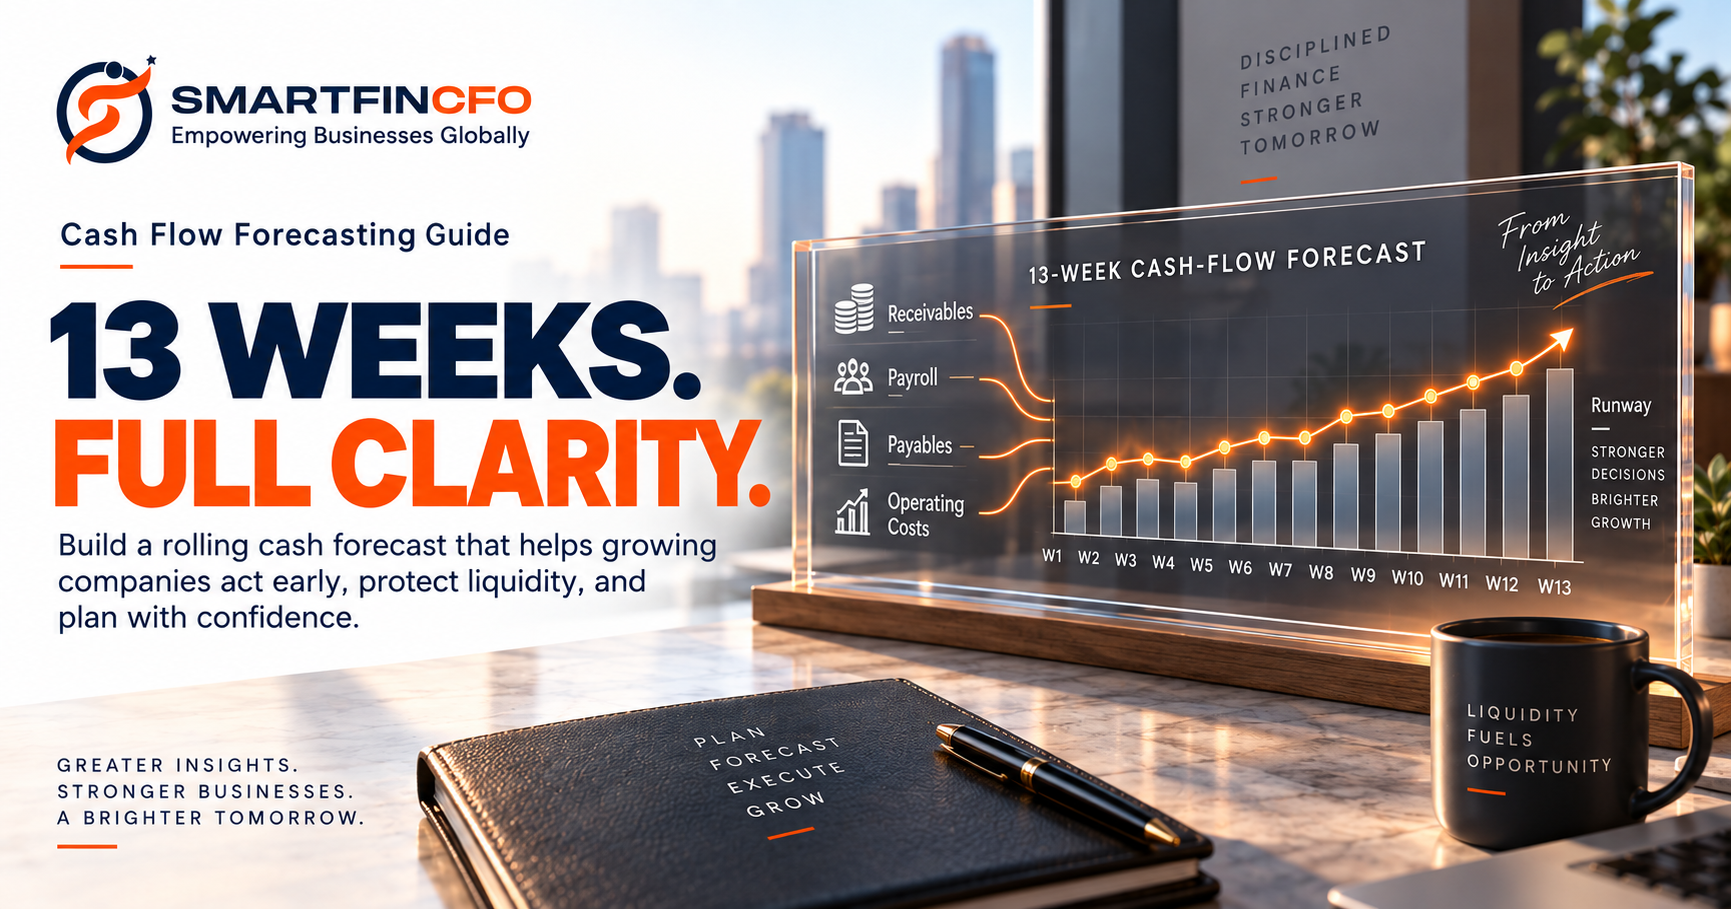
For high-growth businesses and mid-market enterprises, profitability on paper does not guarantee survival. A company can show record operating profits on its accrual income statement while quietly drifting toward an acute liquidity crisis. This disconnect between net income and available bank balances is where traditional budgeting fails—and where an operational 13-week cash-flow forecast becomes indispensable.
A rolling 13-week horizon represents exactly one fiscal quarter. It bridges the strategic gap between day-to-day cash management and long-term annual budgets. By tracking real cash entering and leaving your bank accounts over a 90-day trajectory, leadership teams gain the granular foresight required to navigate supply chain delays, payroll obligations, debt service, and capital expenditures without sudden financial shocks.
In this comprehensive guide, we examine the mechanics of constructing an institutional-grade rolling cash-flow forecast, integrating modern tools, streamlining the management of working capital, and using real-time liquidity visibility to drive strategic enterprise value.
Why 13 Weeks? The Strategic Logic of a 90-Day Horizon
Many executive teams rely either on a standard monthly Profit & Loss (P&L) statement or a simplistic 12-month budget model. While annual models serve strategic planning, they obscure short-term cash volatility. Conversely, daily cash trackers lack the forward-looking runway needed to negotiate supplier terms or secure credit facilities in advance.
The 13-week framework solves this dilemma through three specific operational advantages:
- High Operational Granularity: Thirteen weeks gives sufficient visibility to map specific accounts receivable (AR) invoices to expected collection dates and accounts payable (AP) commitments to actual disbursement runs.
- Immediate Lead Time for Intervention: If a liquidity deficit appears in week 8 or 9, leadership has 60 days to accelerate collections, pause non-critical vendor disbursements, draw down an existing credit line, or restructure purchase orders.
- Alignment with the Quarterly Operating Cycle: A quarter is standard for corporate reporting, tax prepayments, debt covenant reviews, and performance bonuses. Aligning cash modeling to a quarterly cadence ensures executive alignment.
+-----------------------------------------------------------------------+
|                      THE 13-WEEK PLANNING HORIZON                     |
+-----------------------------------+-----------------------------------+
| Weeks 1 - 4: Operational Certainty| Weeks 5 - 8: Committed Operations | Weeks 9 - 13: Trend Projections   |
| Actual AR invoices due            | Scheduled supplier runs           | Pipeline-driven billings          |
| Confirmed payroll & fixed debits  | Approved purchase orders          | Variable operating disbursements  |
+-----------------------------------+-----------------------------------+-----------------------------------+
Core Pillars of Effective Cash Flow Management and Forecasting
Institutional-grade cash flow management and forecasting relies on a direct cash accounting methodology rather than indirect accrual reconciliation. Instead of adjusting net operating income for non-cash expenses like depreciation, you track gross cash inflows and gross cash outflows across operational categories.
1. Opening Cash Position
Your starting point must be consolidated across all liquid operating accounts, money market funds, and sweep accounts on the morning of Day 1. Exclude restricted cash or collateral reserves that cannot be used for operational disbursements.
2. Operational Cash Inflows
Forecasting inflows requires more than multiplying projected sales by an estimated collection percentage. Inflows should be stratified into distinct tiers:
- Billed Receivables: Specific outstanding customer invoices scheduled based on historical Days Sales Outstanding (DSO) and customer-specific payment behavior.
- Unbilled Work-in-Progress (WIP) / Milestones: Contractual progress billings scheduled according to deliverable completion milestones.
- Recurring Subscriptions / Retainers: Contractually guaranteed recurring revenue, adjusted for historical churn and payment processor timing.
- Non-Operating Inflows: Tax refunds, asset liquidations, grant disbursements, or investor capital infusions.
3. Operational Cash Outflows
Categorize disbursements by payment type, priority, and flexibility:
- Payroll and People Costs: Net salaries, contractor disbursements, payroll taxes, benefits, and statutory retirement contributions. (Non-negotiable timing).
- Essential Operations & COGS: Critical raw material suppliers, software hosting infrastructure, and inventory replenishment required to fulfill orders.
- Discretionary Operating Expenses: Marketing ad spend, professional consulting, travel, and non-essential office overhead.
- Debt Service & Obligations: Principal repayments, line-of-credit interest, equipment leases, and tax payments.
4. Ending Cash and Net Liquidity
The net cash flow for each week (Total Inflows minus Total Outflows) is added to the opening balance to establish the closing cash position. Comparing this number against your board-approved minimum operating liquidity reserve reveals whether your business is accumulating cash or burning operational runway.
Step-by-Step: How to Build Your 13-Week Rolling Cash-Flow Forecast
Building an actionable rolling cash-flow forecast requires structured financial design, disciplined data gathering, and weekly operational governance.
Step 1: Establish Your Data Architecture and Taxonomy
Design your cash sheet using distinct operational line items rather than standard chart-of-accounts codes. Group line items logically so that functional department heads (Sales, Marketing, HR, Procurement) can easily validate assumptions without needing deep accounting expertise.
Step 2: Extract and Clean Sub-Ledger Data
Accurate forecasting cash flow starts with audit-ready baseline data. Pull the following source reports from your accounting and banking systems:
- Detailed Accounts Receivable Aging report with payment terms.
- Detailed Accounts Payable Aging report with vendor early-payment discounts and hard cutoff dates.
- Sales pipeline data with weighted probabilities and expected contract signature dates.
- Standard recurring payroll runs and tax calendar.
Step 3: Apply Practical Realism to Inflow Modeling
Never assume every invoice will be paid exactly on net-30 terms. Apply behavioral weighting:
Projected Inflow = Invoice Face Value × (1 − Historical Bad Debt Percentage) × Collection Timing Factor
For enterprise customers that consistently pay 15 days late, adjust the cash arrival to week rather than the invoice maturity date. This pragmatic approach prevents artificial liquidity spikes that lead to flawed spending decisions.
Step 4: Schedule Outflows by Priority Tiers
When modeling disbursements, establish a three-tier payment hierarchy:
- Tier 1 (Non-Negotiable): Payroll, statutory taxes, debt service, facility rents, mission-critical infrastructure.
- Tier 2 (Strategic Vendors): Key inventory suppliers, direct contractors, and client-facing technology.
- Tier 3 (Flexible/Discretionary): Capital expenditure projects, discretionary advisory services, internal events, and expansion hiring.
Step 5: Implement the Weekly Rolling Cycle
A static model becomes obsolete in seven days. The model must be rolled forward each week:
- Reconcile Past Week: Replace the previous week's forecast with actual bank inflows, actual disbursements, and the resulting actual ending cash balance.
- Perform Variance Analysis: Compare projected cash movements against actuals. Identify variances exceeding 5% to discover hidden billing bottlenecks or operational leakage.
- Drop Week 1, Add Week 13: Shift the horizon forward by one week, incorporating updated sales pipeline milestones and revised vendor invoices.
Transforming Cash-Flow Planning into Executive Decision-Making
A liquidity model is not merely a tracking report; it is an executive navigation system. Leaders utilize cash-flow planning to evaluate critical cash-flow decisions under varying market conditions.
1. Evaluating Timing on Capital Investments and Hiring
When considering new full-time hires or major equipment purchases, stress-test the model by inserting the expected costs across the 13-week curve. If the additional expenditure pushes the ending cash balance below your minimum operating reserve in weeks 6 through 10, leadership can defer the starting date or structure milestone-based vendor payments instead of a lump sum.
2. Supply Chain and Inventory Negotiations
With full visibility into projected cash deficits, procurement teams can negotiate strategic supplier payment terms. For instance, shifting payment terms from net-30 to net-45 during a seasonal inventory ramp-up can preserve thousands in working capital, avoiding expensive short-term bridge loans.
3. Scenario Planning and Stress Testing
Robust forecasting of cash flow incorporates scenario analysis to assess business resilience:
| Scenario | Assumptions Applied | Operational Action Plan |
|---|---|---|
| Base Case | Historical DSO, planned payroll, scheduled marketing spend | Maintain standard vendor disbursement cadence |
| Delayed Collections (-20%) | Key enterprise clients delay settlement by 30 days | Freeze discretionary travel, draw revolving credit facility |
| Severe Revenue Contraction | Pipeline closings drop 40%, immediate margin pressure | Implement spending gates, renegotiate Tier 2 vendor contracts |
Optimizing Working Capital Management
Effective capital working management directly fuels enterprise liquidity. The 13-week forecast exposes operational inefficiencies across the three components of the Cash Conversion Cycle (CCC):
Cash Conversion Cycle = Days Sales Outstanding (DSO) + Days Inventory Outstanding (DIO) − Days Payable Outstanding (DPO)
Accelerating Accounts Receivable (Reducing DSO)
- Implement automated payment reminders and payment links on digital invoices.
- Offer structured 1–2% early-settlement discounts for clients paying within 10 days.
- Establish a clear collection escalation matrix for accounts past 15 days overdue.
Rationalizing Payables (Optimizing DPO)
- Align vendor payment runs to a bi-weekly disbursement schedule rather than issuing ad-hoc payments.
- Negotiate extended credit terms with high-volume suppliers based on reliable transaction history.
- Review automated recurring subscriptions quarterly to cancel unused software seats and redundant tools.
Managing Working Capital Reserves
Active management of working capital prevents excess cash from sitting idle in low-yield operational checking accounts while ensuring emergency liquidity is always accessible through structured sweep accounts or revolving facilities.
Leveraging Technology: Accounting Automation and Forecasting Software
While early-stage companies often start with spreadsheet templates, manual data entry introduces formula errors, version conflicts, and delayed insights. Modern finance functions rely on purpose-built software for cash flow forecasting integrated with advanced accounting automation software.
+-----------------------------------------------------------------------------------+
|                     MODERN AUTOMATED CASH ENGINE ARCHITECTURE                     |
+-----------------------------------------------------------------------------------+
|  ERP / Accounting Systems (Zoho, QBO, Tally)  +  Direct Bank API Feeds (Open Banking)|
|                                         │                                         |
|                                         ▼                                         |
|                   [ Accounting Automation & Rule Engine ]                         |
|                     - Automated AR/AP Sub-ledger Sync                             |
|                     - Real-Time Bank Transaction Matching                         |
|                                         │                                         |
|                                         ▼                                         |
|                   [ Cash Flow Forecasting Software ]                              |
|                     - 13-Week Rolling Cash Curve                                  |
|                     - Automated Variance Tracking & Alerts                        |
|                     - AI Scenario & Runway Stress Simulator                       |
+-----------------------------------------------------------------------------------+
Deploying enterprise cash flow forecasting software alongside automated ledger pipelines provides real-time visibility:
- Automated Bank Reconciliation: Connects directly to corporate bank accounts via secure APIs to continuously update actual cash positions.
- Predictive Payment Timing: Uses machine-learning algorithms to predict exact payment dates based on individual debtor historical payment behavior rather than theoretical contract terms.
- Automated Variance Attribution: Automatically identifies whether a cash divergence was driven by billing delays, customer disputes, or unexpected operational costs.
Strategic Impact: Cash Visibility and Business Valuation Services
Liquidity discipline extends beyond risk mitigation—it directly influences company valuation. When investment bankers, private equity sponsors, or independent valuation professionals perform business valuation services, working capital predictability plays a central role in their assessments.
Here is how disciplined cash flow and forecasting systems directly improve company valuation:
- Higher Discounted Cash Flow (DCF) Multiples: Predictable, low-variance free cash flows reduce the perceived risk premium (discount rate) applied by investors, resulting in higher enterprise valuations.
- Clean Working Capital Pegs in M&A: During merger and acquisition due diligence, buyers establish a target working capital peg. Companies with disciplined cash and working capital forecasting avoid post-close purchase price deductions caused by unexpected working capital shortfalls.
- Demonstrated Operational Maturity: A promoter or executive team that presents a rolling 13-week model alongside multi-year growth forecasts signals institutional control, giving lenders and equity partners confidence to deploy capital on favorable terms.
Common 13-Week Forecasting Mistakes to Avoid
Even experienced finance teams encounter pitfalls when building rolling liquidity frameworks. Watch out for these common missteps:
- Treating the Model as an Accrual P&L: Never include non-cash items such as amortization, bad debt provisions, or accrued revenues. Record transactions only when actual currency enters or exits your accounts.
- Ignoring Tax and Statutory Timing: Quarterly corporate advance taxes, sales taxes (GST/VAT), and annual insurance premiums frequently trigger unexpected cash crunches when omitted from weekly disbursement schedules.
- Failing to Conduct Regular Variance Reviews: A forecast that is updated without comparing historical projections against actuals becomes an academic exercise. Regular variance analysis is what refines model accuracy over time.
- Siloing the Forecast in Finance: Sales, procurement, and operations teams must provide regular inputs regarding project milestones, supply orders, and hiring plans to keep the cash forecast grounded in operational reality.
The Complete 13-Week Rolling Cash Workflow
To institutionalize the process across your organization, follow this weekly operational rhythm:
+--------------------+-------------------------------------------------------------+
| Day of Week        | Operational Focus & Deliverables                            |
+--------------------+-------------------------------------------------------------+
| **Monday AM**      | Reconcile prior-week actuals; calculate net ending cash.     |
| **Monday PM**      | Run variance analysis; isolate major collection/spend gaps.  |
| **Tuesday**        | Review AR aging with collections team; update invoice dates. |
| **Wednesday**      | Sync with procurement and HR on pending purchase orders/hires.|
| **Thursday**       | Roll model forward by one week (add Week 13); test scenarios.|
| **Friday AM**      | Present 13-Week Cash Deck to executive leadership for sign-off.|
+--------------------+-------------------------------------------------------------+
Taking Control of Your Financial Runway
Cash flow predictability is the foundation of high-performance financial management. A well-constructed 13-week cash-flow forecast transforms finance from a backward-looking recording function into an active, strategic partner that guides business growth.
By integrating direct cash tracking, disciplined working capital management, and automated accounting workflows, leadership teams gain complete visibility over their liquidity. This clarity enables confident decision-making, protects margins, and builds lasting enterprise value.